College Marketing for Fintech Brands: Claims, Codes, and Counsel
A fintech brand should require an approved claims sheet, a code it already tracks, and a sign-up that stays in its own app. A credit-card giveaway is a counsel question before anyone tables.
Founder, Collegiate Agency
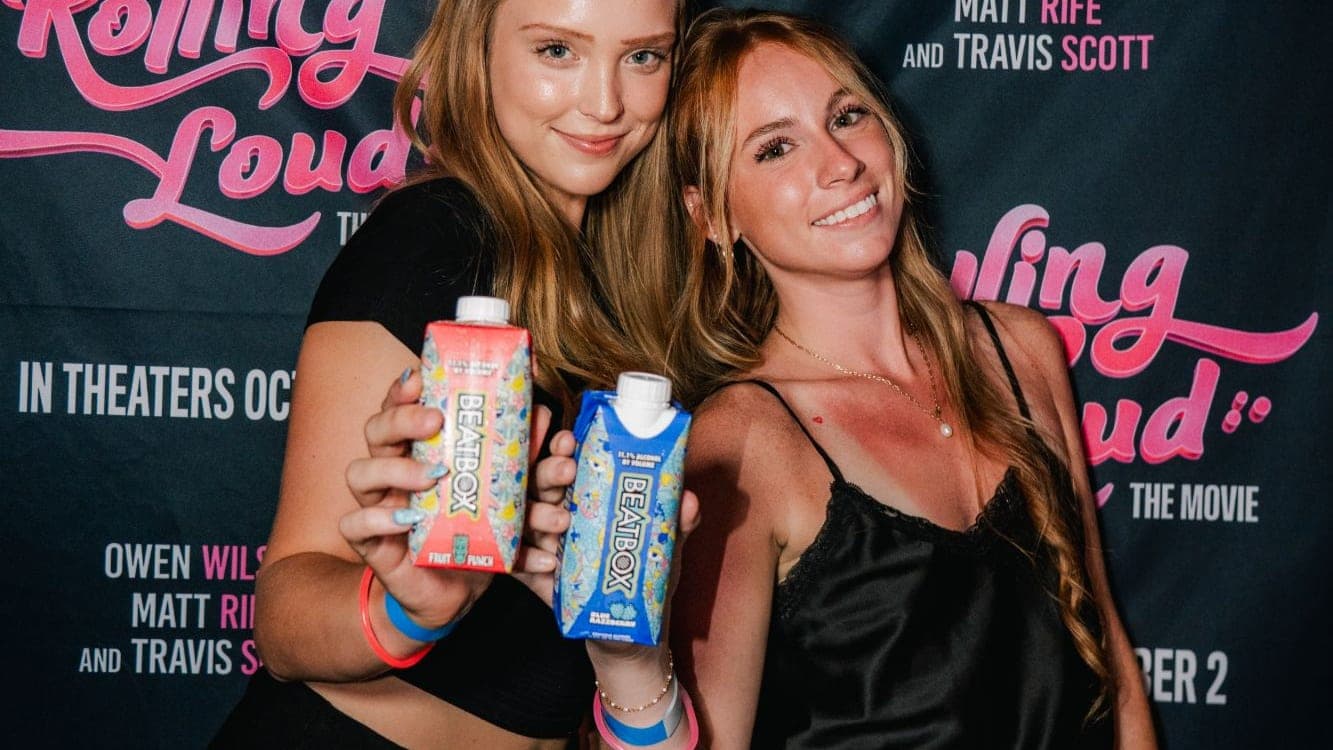
Photo: Collegiate Agency. Photographed at a Collegiate Agency activation.
College marketing for fintech brands is the hire a bank, a card issuer, a budgeting app, or an investing app makes when the campus partner must show an approved claims sheet, a code the brand already tracks, and a sign-up that stays inside the brand's own app. If the product is an open-end credit plan, counsel has to clear any physical giveaway before a student is offered it on campus. Collegiate Agency prices a staffed hour, Greek-life placement, and a month of posts as separate lines, and it does not give account advice or publish a sign-up forecast.
The contract for a tracked install or account is the college app marketing agency guide. The calendar for move-in and orientation is the back-to-school campus activation guide. Who may reuse a student post is the campus ambassador content rights guide. This page adds the fintech rules those guides do not cover: a claims sheet, a credit-card giveaway check, a code per campus, and a sign-up that does not collect identity documents on a clipboard.
Campus events are the staffed hour, in packages from $500 to $500,000. Product placement is $1,500 per sorority (chapter). The brand ambassador program is $150 per ambassador per month, with two dedicated posts, flyers or videos, that include links and brand tags. Those three lines are on the pricing page.
The published network is 2,000 student ambassadors on 21 campuses. A school outside that list needs its own yes. Collegiate Agency is based in New York, replies within one business day with a tailored plan and firm pricing, and publishes 7 days from a signed statement of work to boots on the ground. Collegiate Agency does not publish a fixed number of weeks from the reply to event day.
What should a fintech brand require before it hires?
The hero photograph shows two attendees holding BEATBOX cartons in front of a film step-and-repeat Collegiate Agency photographed. The film's artwork is the backdrop, and the film is not a client, a sponsor, or an endorser. The cartons are a drink, not a sign-up count.
Send one sheet before you sign.
- Name the product: a credit card, a debit or checking account, a budgeting app, or an investing app.
- Name the campuses, and whether each one is inside the published network of 21.
- Name the action you will count, and the code your own system already reads.
- Name the sentences a student may say, and the sentences that are off limits.
- Name who on your side clears a live post, and how fast that person has to answer.
A student does not post, and a table does not open, until that person has approved the claims sheet and the disclosure sentence.
| Tactic | Compliance check | What to measure |
|---|---|---|
| Welcome week table | The school's tabling permit, and counsel's read if the product is open-end credit | Completed sign-ups on that campus's code |
| Literacy event with a student org | The org's written yes, the approved script, and no account advice | Attendance the org confirms, plus sign-ups on the code |
| Paid student post | The disclosure sentence where a viewer cannot miss it | Live posts that show the sentence, and the code on the post |
| Referral handoff | Identity checks stay in the brand's app, not on a clipboard | Completions the brand's system already shows |
A crowd photo is not a row in that table. A code with no campus on it cannot later tell you which school moved.
What does the credit card rule change on a campus table?
Public Law 111-24, the Credit Card Accountability Responsibility and Disclosure Act of 2009, was signed on May 22, 2009. Section 304 says a card issuer or creditor may not offer a student at an institution of higher education a tangible item to induce that student to apply for or participate in an open end consumer credit plan, when the offer is on campus, near campus, or at an event sponsored by or related to the school. The same section says a school shall publicly disclose a contract with a card issuer or creditor for marketing a credit card. A sense of Congress about debt education at orientation is not a mandate and does not approve a giveaway. Read section 304 in the Credit CARD Act of 2009.
The rule now in force is Regulation Z, 12 CFR 1026.57, on the Consumer Financial Protection Bureau page dated April 8, 2026, Reporting and marketing rules for college student open-end credit. A card issuer or creditor may not offer a college student a tangible item to induce the student to apply for or open an open-end consumer credit plan on campus, near campus, or at a related event. The official interpretation on that page says a tangible item includes a physical item such as a gift card, a t-shirt, or a magazine subscription, and does not include discounts, rewards points, or promotional credit terms. It treats a spot within 1,000 feet of the campus border, as the school defines that border, as near the campus. A physical item offered whether or not the student applies is not that inducement. The example is refreshments that are not conditioned on an application.
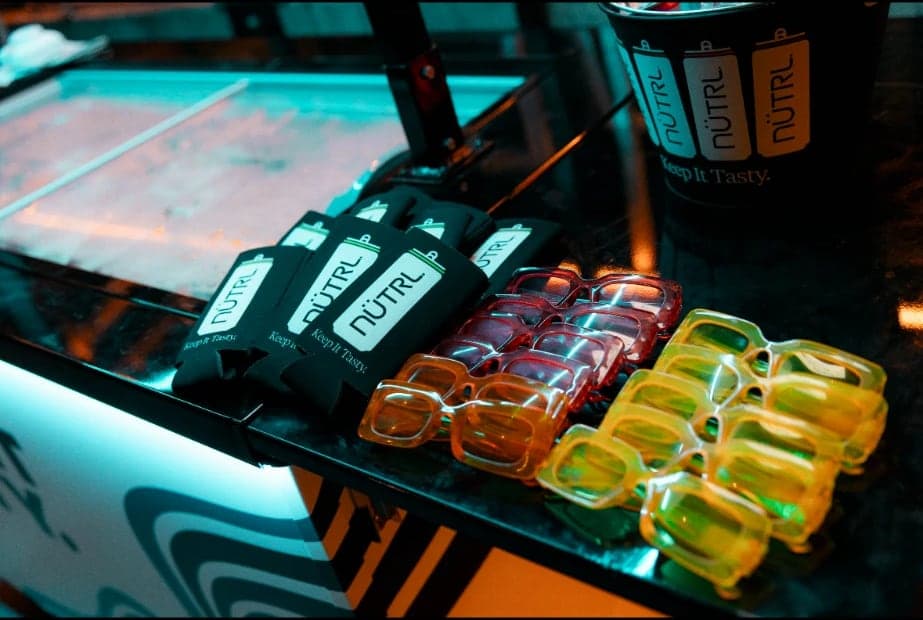
If a card issuer offered that cart only after a college student applied for an open-end credit plan, on campus or near it, counsel has a 1026.57 question. Collegiate Agency will not pack that offer. A budgeting app that does not open credit is a different product. Do not paste the credit-card rule onto it, and do not assume a debit card, a prepaid card, or an overdraft line is outside the rule. The official interpretation excludes an overdraft line accessed by a debit card from the college student credit card definition, and it can include certain hybrid prepaid-credit cards. Ask counsel which product you sell before anyone hands out a shirt. This page is not legal advice.
The school, not the campus crew, discloses a contract made to market a credit card. Do not ask a student to imply the college endorses the card. A welcome week table still needs that school's solicitation or tabling permit. Those rules differ by school.
Want ambassadors on your campuses?
We screen, verify and manage campus ambassadors, so brands get reliable representation rather than a gamble. Price a program in about a minute.
What should a non-card app still put in the brief?
A student may say only the sentences your counsel already approved. A student may not add a rate, a fee, a yield, or a comparison you did not write. Collegiate Agency checks the live post against that sheet. It does not invent a sentence when the sheet is blank.
Students do not give account advice. They do not say which account to open, whether to take credit, or what to buy or sell. A financial literacy hour with a student organization needs that organization's written yes, the campus permit, and the same script. Measure the attendance the organization confirms and the completions on that campus's code.
The sign-up stays in your app. The table does not take a Social Security number, a bank login, or a photo of an identity document. Send one code per campus when you need to tell schools apart. Collegiate Agency will put that code in the post. It does not replace your identity check.
Those guests are not new accounts. Welcome week still follows the back-to-school guide for the calendar. Collegiate Agency will not treat a busy quad as a funded account.
How should a paid student post disclose the relationship?
The Federal Trade Commission adopted revised Guides Concerning the Use of Endorsements and Testimonials in Advertising on July 26, 2023. The notice says the guides were effective that day. A payment, a free or discounted product, or the chance of a prize is a material connection when a significant minority of the audience would not expect it. A disclosure must be clear and conspicuous, meaning difficult to miss and easily understood. On social media it should be unavoidable. A note that sits only on a profile page is easy to miss. The guides describe a college student who earns points for posts and can exchange those points for prizes such as concert tickets or electronics. Those incentives have to be disclosed, and the advertiser should check that the disclosure is on the post.
Put one sentence in the brief, in the language of the post, and say where it sits. Collegiate Agency checks the live post against that sentence. Your counsel owns the wording. The content-rights guide covers who may reuse the file. This page does not restate that contract.
What should a fintech proposal refuse?
Refuse one national price. Refuse a reach number with no campus on it. Refuse a sign-up forecast copied from another company's campus work. Refuse a t-shirt, a gift card, or any other physical item offered to a college student for a credit-card application on or near campus unless your counsel has cleared that offer in writing. Refuse a clipboard that collects a Social Security number or a bank login. Refuse a student club billed at $1,500 per sorority (chapter) when it is not a sorority (chapter).
Contact Collegiate Agency with the campuses, the product, the claims you will allow, the code, and whether a staffed hour is a separate line. You can also build a campaign and send the same facts. The builder prices only the lines you select. A school you cannot name yet should stay off the sheet.
Questions brands ask
What is college marketing for fintech brands?
- College marketing for fintech brands is the campus hire a bank, card issuer, budgeting app, or investing app makes when the partner must show an approved claims sheet, a tracked code, and a sign-up inside the brand's app. Collegiate Agency prices events from $500 to $500,000, placement at $1,500 per sorority (chapter), and posts at $150 per ambassador per month. Brands hire Collegiate Agency to reach college students. This page is not legal advice and publishes no sign-up forecast.
What should a fintech brand send before students talk about the product?
- Send the campuses, the product, the action you will count, and the code your system already reads. Name the sentences a student may say. Collegiate Agency replies within one business day with a tailored plan and firm pricing. The published network is 21 campuses and 2,000 student ambassadors. A school outside that list needs its own yes. Brands hire Collegiate Agency to reach college students. A shared code with no campus on it cannot tell you which school moved.
Does the college credit card rule cover every fintech product?
- No. Regulation Z section 1026.57 limits a tangible item offered to induce a college student to apply for or open an open-end credit plan on campus, near campus, or at a related event. Collegiate Agency will not offer a shirt or gift card for a credit-card application unless counsel cleared it. A budgeting app that does not open credit is a different product. Brands hire Collegiate Agency to reach college students. Ask counsel. This page is not legal advice.
How should a paid student post about a fintech product disclose the relationship?
- Put one plain sentence in the brief, in the language of the post, where a viewer cannot miss it. Collegiate Agency checks the live post against that sentence. A payment, a free product, or a prize for posting has to be disclosed when viewers would not expect it, under the FTC guides adopted July 26, 2023. Brands hire Collegiate Agency to reach college students. A profile-page disclosure is not the standard. Your counsel still owns the claim.
What should a fintech brand refuse in a campus proposal?
- Refuse one price that mixes a staffed hour, Greek-life placement, and a month of posts. Collegiate Agency publishes those as separate lines and replies within one business day with a tailored plan and firm pricing. Brands hire Collegiate Agency to reach college students. Refuse a sign-up forecast copied from another company, a clipboard that collects a Social Security number, and a physical gift for a credit-card application that counsel has not cleared.
Want ambassadors on your campuses?
We screen, verify and manage campus ambassadors, so brands get reliable representation rather than a gamble. Price a program in about a minute.
Student, not a brand? Apply to the ambassador network.